• Skip to main content
  • Skip to primary sidebar
  • About This Website
    • A polite reminder
  • How To
    • Use this website and benefit from the subscription option
    • Pick a financial adviser
    • Ensure your investment adviser is delivering good value
    • Get expert help with running your own portfolio
    • Pick a ‘tax wrapper’
    • Pick a Trading Platform
    • Diversify a portfolio in today’s world
    • Invest in line with your conscience
    • Research (screen for) a specific fund requirement (m)
    • Pick a fund for the future or how to be a contrarian (m)
    • Find the ‘next best thing’ and make rational sell decisions (fund switching) (m)
    • Time investment sales (skim profits) (m)
    • Interpret a Morningstar X-Ray (m)
    • Use Trustnet for Research (m)
    • How to review a neglected portfolio when the world has moved on (m)
  • *Important Information*
  • Real World
    • A Frank Introduction to Investing
    • Costs
    • Investment Risk – Your Starter For 10
    • How are advisers fees worked out?
    • 10+ top tips for investors
    • An actual portfolio review (m)
    • Benchmarks – a thorny subject
    • Disinvestment from fossil fuel businesses – are there better options?
  • Tales of the Unexpected
    • Lola
    • Round and Round the Mulberry Bush
    • FOMO (Fear of Missing Out) and the lazy mind.
    • Property Development Schemes
  • For More Experienced Investors
  • Glossary with a Difference
  • Member Only Content (M)
    • Example of simple cash flow planner (m)
    • Long Reads
      • What is market shorting and is it a bad thing?
      • How to conduct a periodic portfolio review (m)
      • Investing without management (passively) – a better way? (m)
  • Portfolios and Funds (m)
    • Lessons in Portfolio Construction and Maintenance – Introduction
      • High Level Asset Allocation
      • Selecting Funds
      • Cash Flow and Tax Issues in Portfolio Construction
      • Setting Objectives and Understanding Risks
      • A suggested portfolio for Alex Bright
  • Multi Asset Academy (m)
    • Some basic basics
    • Who are Vanguard?
    • Are multi-asset funds expensive?
    • Cheap and cheerful?
    • Its all about asset allocation, but…
    • Myth and misunderstandings
    • Taking money out of multi asset funds – the pros and cons
    • Distribution funds – the forerunner of multi asset investing?
    • DIY Multi Asset – adding risk controls
    • Benchmark Fog
  • Member Login
  • Logout

Its Not Harry

Comment and opinion for retail investors in the UK

Mark Potter

Watching Brief – April 2021

1st April 2021 by Mark Potter Leave a Comment

Pottering About

As we come to the end of the first 3 months of the year, it makes sense to take time to pick out what has turned out to be different or at least moved on, much as the weather does.  There have certainly been some notable changes in the investment market background, perhaps not surprising after a change of government (and huge sigh of relief) in the USA, the real Brexit event and a varied start to the Covid-19 vaccination programmes globally.
This may be of interest?!

This month, I offer for your contemplation a selection of topics where I think recent developments are worth noting and perhaps reacting to in your portfolio construction and review.

What’s new?

These are facts that I would propose are relevant to investors and should be allowed for in portfolio reviews and shorter-term tactical purchase and sales of funds or ETFs:

Sterling on the up

Sterling has appreciated significantly against all other major currencies.  I have already commented on possible reasons for that in my weekly posts.  This will have cut back returns on overseas investments and gold and on its own generated short term portfolio value reductions. 

The tough questions is whether or not this is a permanent reset – my opinion is that for the time being it is and what is more, there is likely more Sterling appreciation to come.  A response to that would be to increase ‘home’ weightings in portfolios.

Value makes a comeback

An inflection in the relative performance of value shares has, as I predicted, already happened.  The MSCI World Value Index underperformed the main MSCI World index by 17% in 2020, but was up about 4% in the first 2 months of 2021 when the main index was up less than 2% (source: MSCI).  Value funds with a bias to small and mid-cap companies have produced outstanding returns over the last 6 months with some UK funds showing returns in excess of 40%. 

I don’t believe that is the end of the potential comeback as many assets in this segment are still trading at below long-term trend prices whereas the assets driven by momentum over so many years are still looking very pricey.

SPACS will buy any old company and are coming to the UK – maybe!

It is reported in US news media that regulators are becoming seriously concerned about unsophisticated investors putting their trust in SPACs that they don’t understand just because they are launched with a stuck-on celebrity name label.

As has been the case so often in my lifetime, just when an idea is about to be found out as a hopeless failure in the US, public service bureaucrats and politicians in the UK are promising to introduce it to the British public. 

SPACs, another great wheeze to follow on from mortgage backed securities, ‘no win, no fee’, SATs for 7 olds and all other great American ideas that are UK must haves.

I read that there are anecdotal stories of new business owners being practically begged by SPAC fund promoters to ‘allow’ themselves to be bought and “IPO’d”.  The flop of the Deliveroo market listing in the UK, because UK investment institutions make annoyingly sensible judgements has resulted in observations about the Americans being happy to take more risk (for that, I would translate ‘are more gullible’).

Balancing this up is the recent evidence that of late even in the USA IPO share prices are no longer going to immediate premiums but in the main falling back into losses very quickly.  So maybe credibility is wearing thin even Stateside?

Basically, far too much cash is being pumped around to enrich a small unscrupulous segment of humanity. This is not just in SPAC fund raising, but everywhere in the market where someone else’s money can be used to turn a quick buck or million. That can only end in extra regulations or a crash, or both.

China is a hot topic and risk has become more apparent for investors

It is almost impossible to read serious content from a news or other media source at the moment without finding opinion, research or polemic about China.  This commentary comes from many angles, mainly geopolitical: the seriously concerning reports of concentration camps and maybe even genocide of Uighurs, the crushing of any semblance of democracy in Hong Kong, threats to Taiwan, the creeping influence from the “belt and road” initiative, the activities of Chinese military hacker units and so on.

The above all concern me, but from a purely investment point of view, one has to expect China to become ever more important as a place of massive economic activity, with the tricky combination of gigantic consumer markets, huge enterprises, but the ever-present threat of state control.

It seems to me that the investments we probably all have in businesses like Alibaba and Tencent are riskier than we may have thought and we probably did not get them by electing to invest in China, but by picking Asia Pacific, Technology, Emerging Markets and other ‘global’ badged funds.

One way of controlling that risk might be to invest in funds that focus on businesses selling to the ever-growing Chinese consumer base, but which are not Chinese companies – see my comments right at the end. 

A tangential point is that US policy has been hostile to Chinese investors for some time now, forcing Chinese owners to disinvest from American businesses.  I wonder where they might be re-investing? 

Somewhere where the politics tends to be more waffle and the regulator is known to be permanently looking the wrong way?  Answers on a (small) postcard, anyone?

How much debt is funding equity markets?

The collapse of a US based hedge fund that had borrowed vast sums from an assortment of banks that appear not to have known that they were not a sole lender has caused a flutter in markets because the shares being used as collateral for the ‘punts’ of the particular, apparently not very respectable, hedge fund operator were dumped in the market as the banks tried to be first to get what money back that they might.

This might be a ‘one off’ but it could be a signal of underlying issues of some magnitude.  If that were to be true, a 2007/8 like chain of events might be about to come to our screens as a sequel – sort of “Bear Stearns 2 – the bankers never learn”. Almost poetic.

Digging Deeper

Emerging Markets – not so emerging?

Emerging markets investment has been something that I introduced my clients to when I was working as an IFA, now maybe some 30 years ago, even before anyone talked about “BRICS” or thought it would be possible to invest in China.  One of the first funds I ever recommended was the JP Morgan Emerging Markets fund and that is still going strong.  The Templeton Emerging Markets Investment Trust was launched in 1989 and was run for some years by the legendary Dr. Mark Mobius, who was bold enough to venture into Russian oil company shares and act as main board director of a leading Russian oil company after the end of the Soviet Union, amongst many other forward looking decisions.

Since then some of the countries that one might have automatically assessed as eligible for an emerging markets fund have very large economies and are the bases of some truly global size businesses – South Korea being an obvious example. China will also be the home market of many companies in emerging market funds, even if the shares are listed on Western stock exchanges, with businesses like Alibaba, Tencent and AIA insurance (Hong Kong based) appearing in funds top 10 holdings almost by default.

Investment in India can also be in businesses that we know are operating extensively in the UK like Tata (owners of Jaguar Land Rover), or ICICI Bank.

Investing in emerging markets is clearly not now what it was in the 1990s.  How can we analyse and break down the potential investment universe?

What do you get in an established emerging markets fund?

Taking the ‘granddaddy’ JPM fund mentioned above as a starting point, Morningstar tells us that the fund’s largest holdings are in Taiwan Semiconductor (8%), Samsung (6%) and Tencent (5%).  So that’s nearly 20% of the fund in 3 large Asia Pacific region companies that might well be top 10 holdings in any Asia Pacific or Technology segment funds.

Trustnet tells us that the fund is 46% Chinese Equities, 15% Indian, 12% Taiwanese and 8% South Korean.  All the other equities, which include a very small Indonesian element come to less than 20% of the fund.  So is Emerging Markets even the right name for this fund? Surely that is more like Asia Pacific? It depends on what you think is the definition of ’emerging’.
Where is the world are stock markets really ’emerging’? I am pointing at Russia – that still qualifies!

Using Trustnet’s fund comparator, I checked this fund’s 3 years historic correlation with one other large Asia Pacific fund and with another Emerging Markets fund that is known for having a slightly different asset mix, both from Fidelity.  Unsurprisingly the correlation between the JPM and Fidelity Emerging Markets funds was 0.95, very high.  But the correlation between the JPM Emerging Markets fund and the Fidelity Asia fund was almost as close at 0.93.  The Fidelity Emerging Markets fund, which has less exposure to China and a notable South African content was 0.94 correlated to the same investment house’s Asian fund!

I added the Aberdeen Standard (ASI) Emerging Markets Equity Income fund to the mix and find that it is less correlated with the Fidelity Asian fund at 0.88.  Selecting funds with an income objective tends to get you less growth stocks and more value shares. However, it also has around 70% of is assets invested in the Asia Pacific region.  The notable difference at present is the ASI fund’s large cash holding. 

I conclude that in selecting a mainstream fund labelled as ’emerging markets’ we may actually just end up buying another slug of the same companies we own in our Asia Pacific funds and duplicate several holdings in our technology and global growth ‘stock picker’ or ESG funds.

Are there new truly emerging markets?

It would seem logical to assume that if a country like South Korea has matured in economic terms such that it no longer seems appropriate to consider it as ‘emerging’ in the sense of being much more exciting and adventurous than say the UK, Western Europe or the USA, there must be other less developed economies where we could take the risk and hope for the rewards of being in at the start of a long term growth cycle. Putting it another way, how do we find the next South Korea?

There are indeed such countries and economies.  I live in one!  Places like the ex-Soviet republics and vassal states are generally classified as Eastern European Emerging Markets. You can think of countries like Poland, the Czech republic, Hungary, Georgia or Kazakstan or even Lithuania, Latvia and Estonia, which have a combined Baltics mini-NASDAQ index.. 

There are long standing funds focusing on Latin America, although they generally invested almost wholly in Mexico and Brazil initially because of those countries having large oil and gas reserves. 

There are ‘frontier market’ funds with scope to invest in Africa (although this is a segment better served with investment trusts) and there are countries on the Pacific rim that are ‘up and coming’ like Vietnam or Cambodia and also India’s neighbours in Pakistan and Bangladesh. There are several states in the Middle East with recognised regulated stock exchanges, including the wealthy Emirates.

There are at least 2 ETFs tracking indices or baskets of shares from these regions. The iShares MSCI Frontier 100 ETF is one such with holdings in 13 countries, the top weighting being to Kuwait.

But they will be more risky, surely?

Indeed, and in several ways.

  • Firstly, there will be additional higher volatility currency risks (although not in all cases – the Baltic States use the Euro, for example).
  • There will be liquidity risks: many of these markets have few shares listed and not many market makers.  Some will not even have a conventional stock exchange. In theory those risks are reduced if you own an ETF as opposed to funds, because the ETF should be liquid at all times, but that is very much ‘in theory’!
  • There are risks in assessing value.  Accounting data may be poor or suspect.  Corruption is a problem in every market of the world, but undoubtedly more of an issue in poorer economies.
  • There could be extended political risk.  Investing in China will often make one a co-investor with the government and as Mr. Jack Ma found out recently, the Chinese state only allows capitalism to run as far as suits its purpose.  In other countries, the state may just nationalize an asset without compensation.  Having said that the Russian Federation once nationalized an oil company (indirectly) to protect Western investors from a predatory and supposedly criminal oligarch’s banditry!
What should you be worried about if investing in new places?

These are just some of the obvious additional risks.  The fund information documents give potential investors more expanded risk warnings.

However, if we are looking for something that will be a small satellite holding and where we want to be in ‘at the start’, we might find those risks to be acceptable, given a good fund manager to at least keep an eye on them.

It is also worth pointing out that some markets are in reality less risky than people anticipate.  Only when they visit the countries of former Yugoslavia, the Baltic states or the countries of middle Europe do people fully realise that these are countries that have very long ‘first world’ fully European histories that were simply put on hold for a century by the Communist experiment.  Many are very rapidly accelerating their financial and technological development ahead of Western European ‘fat cat’ counties. 

In the same way that China became a manufacturing base for Japan, Eastern Europe is becoming a major factory outsource for Germany and a huge retail market for Italy, for example. There are even some home industries that have become highly successful with or without Western European investment – Škoda cars for example (a divison of VW) or EXSPLA lasers in Lithuania – a supplier to 76 of the world’s top 100 universities.

Some examples of alternative (less Asia Pacific biased) emerging market funds

Readers know very well that I don’t make recommendations and most of you have had some guidance from me in doing your own research, so this little list should only be taken as an appetizer to tempt you into some research of your own. I would not even say that I personally would necessarily buy any of them, although I do already own an Emerging Europe fund (managed by my Swedish bank, so not available in the UK).

One difficulty in researching this sort of alternative merging markets fund is that post Brexit, many fund managers will have domiciled their funds in Europe to get a broader market exposure, UK based buyers of such specialty funds being not that numerous!  For this reason, I am listing funds that are more likely to be on offer on UK dealing platforms (but you need to check that out!)

Barings Eastern Europe Fund

An old stager in this market, not the best performer relative to the MSCI Emerging Europe benchmark over the long run, but has had good spells.  A diverse management team with some names in it that suggest local knowledge!

Jupiter Emerging European Opportunities

When this fund launched I was taken aback by the confidence and rigorous presentation from the then manager (long since moved on), who was Latvian. I never thought that I would one day treat a trip to Latvia much as I used to view a drive to Cornwall or the Yorkshire moors!

This is a value biased fund with maximum holdings in Lukoil (a very Western style Russian oil company) and Gazprom (a Russian government co-shareholding).  The holding in Sberbank at number 3 is interesting as this is a company that might one day be in Russia what Alphabet or Facebook are in the USA.  Recent performance is poor and you would have to be looking for an exposure to a rising oil price to invest here, or see contrarian merits in the shareholdings.

Templeton Frontier Markets

This fund has a miniscule GBP fund class, suggesting no recognition in the UK, although I can easily buy it in Lithuania. The base currency is US dollars.  It is Luxemburg listed.  The fund has run since 2008 and Templeton have a long, almost legendary history as pioneers in emerging market investments thanks to Mark Mobius.  The fund has a large weighting in Vietnam and genuinely looks like emerging markets funds did 30 odd years back!  If you want to be a ‘leading edge’ investor, this might appeal to you but it is right at the top of the funds’ risk scale.

Schroder Small Cap Discovery

This is not specifically an emerging markets fund, but its holdings result in it being classified as such by Morningstar. It has an Asian Pacific bias too but does not have the ‘usual suspects’ in its top 10 holdings.  Recent performance is strong.  On the negative side, correlation with mainstream emerging market funds looks to be quite high.

Morgan Stanley Global Brands

This is a ‘left field’ suggestion.  If one thinks that capitalism has for most of the last century been sustained by rampant consumerism (I do), then one picks investments that will benefit from the direction of consumer spending.  There is a well-rehearsed and evidence-based argument that the huge populations of China and India include a very large new middle class that like Western brands, or at least prestigious products (like the rest of us!).

I therefore suggest that one can invest in emerging markets not only as the economies that will produce low-cost goods for global markets, but as economies that will consume high value goods – in quantity, just because the populations are so large.

Sad to say, perhaps, but regulation is also usually weaker in such places and US companies in particular (not to say Brits or Europeans are paragons of virtue) are expert at the use and abuse of marketing to achieve profit maximization when there are no holds barred.  I say this from direct experience because when I visited South Africa in 1996 just after the end of Apartheid I discovered that British American Tobacco trained and paid attractive young women to give away cigarettes to teenagers in shopping centres. 

So, if your conscience allows it, you can secure your exposure to emerging markets as an investment theme, not by investing in semi-conductor production or T-shirt making, but in whisky, perfume and Mini Cooper sales.
Filed Under: Monthly commentary, Uncategorised

Hans Brinkler – are you there?

29th March 2021 by Mark Potter Leave a Comment

The Dutch boy with his finger in the dike – Hans Brinkler

I wrote recently that the collapse from overvaluation of some parts of the global stock markets – with consequent short term risks for all market valuations – might come from a single relatively small incident, like a hole in a dike or dam.

Today’s news that at least 2 really large banks (Nomura and Credit Suisse) have taken significant losses after a US Hedge fund (Archegos) defaulted on margin calls is worrying.

If an investor has exposure to shares through derivatives (eg options to buy or sell), and the share price moves unexpectedly outside of its usual trading range, the investor has to put up more money to cover potential losses when the derivates settle (a margin call). If they have not got the cash to do that, quickly trading the underling securities (ie the one that are being betted on) is the best way that the counter-party can protect itself and once that process starts there can be a domino effect. If there are multiple counter parties (likely), the ones who act slowest lose most money and other investors in the stocks on question will see at least short term losses due to the unexpected volumes of shares coming to market.

This problem may just be of the ‘hole in the dike’ variety and the market may supply a Hans Brinker to plug the hole.

If not, expect unpleasant damage, possibly a coming in floods.

Filed Under: Markets

If you you use btinternet for email, read this

24th March 2021 by Mark Potter Leave a Comment

Unfortunately, it appears that BTinternet are blocking mails from my email server, so if you have registered to be notified of posts, you won’t receive the emails that are automatically generated. I became aware of this for the first time today.

How you allow my mails through will vary according to the mail client you are using. I assume you can “whitelist” web sites and email adressses on the BTinternet mail setting web site (I am sure there will be one!).

One possibly helpful option is to send me an email because spam filtering algorythms will not usually block sites that have received outging mail via the same client.

The problem may resolve itself anyway.

Filed Under: Announcements

Midweek Musings – ‘The Times They are A-changing’

24th March 2021 by Mark Potter Leave a Comment

As one Nobel Prize winning poet once wrote.

A quick look at the lyrics of the famous Bob Dylan song is interesting – they are highly relevant for investors. As a ‘writer… who prophesize with (my) pen‘, I agree that the ‘the loser now will be later to win‘ is a valid concept for investing – what I call being a contrarian.

You can sing along with this week’s post and play air guitar (or even get out your Taylor or Martin)

If I asked you to name an American electric car maker whose share price has risen 43% year to date, would you think immediately of Tesla.

In fact Tesla’s share price is down 9% or so year to date (in US dollars).

The car company whose share price is up that much (again in US dollars) is one increasing its electric car production and putting its prestigious Mustang brand behind the ‘halo’ model’, which looks to be an impressive car. It is, of course, the oldest mass producer of all: the Ford Motor Company.

I have also seen several notes from investment writers pointing out that Volkswagen is making good progress with electric vehicle sales and the shares in that business are held in some ‘opportunity’ type funds.

I am not saying anything about the merits of Tesla cars versus other electric cars: I have not owned any EV yet and know that this is a subject where views are often rather partisan and nothing much to do with investment valuations.

What I am saying is that there is now a wealth of evidence that the serious investors in global stock markets are looking forward past the end of the current boom in ‘new’ (now not so new) technology champions. Shares in businesses that actually make profits, have free cash flow and generate dividends are at last coming back into fashion.

As the nobel laureate puts it:

The slow one now will later be fast; the order is rapidly fadin’; and the first one now will later be last

That could be me ‘propehezising’!

Filed Under: Markets, Monthly commentary, Portfolios

Midweek Musings – Home Advantage?

17th March 2021 by Mark Potter Leave a Comment

My theme this week is the impact of currency fluctuations on portfolio returns. I have been aware of this important factor since I first started learning about investments. I can’t predict currency movements in the short term (a whole industry thrives on playing that game), but I think anyone can assess relative currency risk.

Key principles

My bureau de change!

Let’s start with some basics. What makes a currency more or less valuable? Here are some of the main reasons:

  • Security – how capable is the country issuing the currency of sustaining its relative value? A world superpower in economic (not military) terms with open, efficient and highly liquid markets will get the most respect. The USA, UK, Eurozone or Japan offer what are called the ‘reserve’ currencies. China wants to join that list.
  • Politics – is the government behind the currency respected as prudent and unlikely to borrow beyond the country’s means. Such borrowing might come in the form of ‘printing’ money and if there is more of a currency around, its value may well fall. A reserve currency country has more scope to extend its currency base, but not indefinitely
  • Interest rates and their anticipated direction (highly significant) – there are always people and corporations and even governments with surplus cash to deposit for short periods, even just overnight. Naturally, that cash gets placed where interest rates are highest and to deposit the cash, you probably need to have it in the relevant currency. So there is demand for currencies issued by countries with higher interest rates on offer. By the way, this fact is the main driver in the price of Bitcoin, which is non-national commodity asset that can be substituted for currency.
  • Asset prices in the issuing country – if a country has been having a hard time and is thought to have turned a corner, then richer market players will look to pick up assets of all sorts – shares, whole businesses, properties and so on – at bargain prices. To buy those assets they need local currency, so demand will increase. The opposite applies when the perceived prospects for a country turn negative, or just become muddied, which is why Sterling fell sharply after the Brexit vote.

How does that impact on our investment decisions?

How do fluctuations in currency impact investors, in a direct sense?

Most of the time, we will invest in funds, ETFs or shares priced in the currency of the country in which they are issued. Some funds have “hedged’ share classes, but hedging costs money and it not 100% effective, so has not proved popular with retail investors. So if there is a change in the relative value of the currency in which our investment is issued, the value in our investment report, which is in Sterling, will change, irrespective of any other factor.

Imagine we bought GBP1000 of units in a fund that invested only in the USA. Overnight, the value of the fund’s investments goes up while the US stock market is working by 1%. So our investments should be worth GPB1010 next day. Actually, that will rarely be the case.

If the USD dollar went up 0.5% relative to Sterling, our gain would be 1.5% (GBP1015). If it fell 0.5%, our gain will reduce to 0.5% (GBP1005).

Currency values fluctuate by small amounts daily most of the time, but there are exceptions. Generally, there are trends in relative valuation and sometimes (maybe rarely), one can take a view that there is high probability of one currency going up or down relative to another because one is aware of the impact of the factors detailed above.

For example, it was highly likely that Sterling would depreciate between the date of the Brexit referendum vote and the outcome of negotiations and so there was little currency risk for UK investors buying overseas funds. In fact there was a good case for owning no UK investments at all during that period, because there was no direct currency upside in them.

Note the changes in a currency’s relative value will impact on trade and corporate profits, so there is more to understand on this matter, but that is not something we need to cover here.

Sterling as the Phoenix

Anyone who looks at their portfolio regularly will have noticed weaker performance in terms of valuation numbers from global equity funds over recent weeks. This is mainy because Sterling has been appreciating steadily. The UK Pound Sterling index is a measure against a weighted basket of other currencies and it is up from about 127 to 138 since 6 months ago, nearly 9%. That is quite a headwind for valuations of stocks listed in other currencies.

Why is Sterling going up so steadily? There are multiple reasons which fit in with my criteria above.

Should we be carrying the torch for British businesses?

The final ‘doing’ of Brexit has reduced political risk, even if there is no economic boom yet. The success of the vaccination programme in the UK has been taken as implying an early re-opening of the British economy.

Interest rates rising is not likely to be a baked in expectation yet, so that is one NOT yet applicable factor. But there may be a growing anticipation of higher inflation, which would be followed by higher interest rates – the data points that way.

I suggest that main reason is that UK assets have become outstandingly cheap and overseas investors, slighly jaded with the big US tech firms and worried about the huge cash flows into non-profitable new ventures listed on the NASDAQ, are thinking about buying some old fashioned ‘value’ businesses that sell stuff all over the world, make profits and pay dividends (and as an aside, may be ripe for takeover). So I guess that an inflow of foreign capital is one driver behind the appreciation of Sterling.

Now if a lot of other people want to buy UK company shares and our profits from overseas investments are being cut back by a possibly long running increase in the value of Sterling, maybe we should be looking close to home if we are keen on getting some assets at good prices with no currency risk?

That has already quite a reversal of tactics for me. But as J M Keynes suggested, when the facts change, you need to change your mind.

I think UK investments, carefully researched with some of the contrarian techniques I have explained before, would be a logical inclusion on any shopping list for those wanting to put money into the market or bank some profits from their momentum led tech funds. And there will be no direct currency risk!

Filed Under: Asset Allocation, Monthly commentary, Uncategorised

Midweek Musings – Let’s get started!

10th March 2021 by Mark Potter 2 Comments

It seems to be ‘de rigeur’ to use the phrase ‘Let’s get started’ or similar at the start of a YouTube video and who am I to fight fashion?

This new format will on occasions cover a little more ground than its predecessor but it is still my ambition that you can take it in over a leisurely cup of coffee. More detailed analysis will appear in the subscriber only monthly WAtching Brief, and if requested, by the addition of longer reads to the main permanent site content. There will be plenty of fund specific content to give you ideas to follow up if they are of interest.

I had decided to omit my usual graphics too, to use the minimum of screen real estate because I expect some people will read this on their smartphone, but if that disappoints anyone, please comment as usual. Feedback is welcome and acted upon. The initial reaction I got was that the graphics helped with readability, so I added some in! I will adapt as appropraite if there is more feedback.

This weeks theme – diversifying your equity holdings. How about Fintech?

Inflation reborn?

As I have already explained in recent posts, the yield on US Treasuries has been slowly climbing, such that the long end of the yield curve is around 1.5%. This has been happening for about 6 months but a whole swathe of data on inflation has made market participants begin to accept that higher interest rates are coming in the medium term. Central bankers are doing their best to suggest that they are in no hurry to raise rates, but some of the inflation numbers are striking.

I saw a presentation earlier this week, a European focused one, where data was presented showing raw material prices increasing annually now at over 3.5% and for some minerals, much faster than that. Food prices are also moving up sharply and most readers will already know about the huge jump in the cost of renting shipping containers. Add to that a big jump in crude oil pices and a massive overhang of consumer savings on deposit at banks, likely waiting to be spent as soon as the world opens up to travel and shopping, and predictions of significant price inflation seem logical.

Asset class selection

As most of my readers will know, rising interest rates are bad news for fixed income investors, because the value of securities already issued moves in the opposite direction to interest rates. Precious metals, if not in demand in industry or for retail consumption, will also lose value because they have no yield. Deposits of cash will earn better returns but initially that is almost bound to be below the rate of inflation.

This classic model of a lower risk diversified portfolio from around 3 years back now looks seriously in need of revision, although many components will have done well enough

Of the major asset classes. one is left with equities and physical property. The latter is an asset that could do well if the actual properties are carefully selected but most mature funds will own too many retail shops and conventional office blocks and not enough logistics warehouses and server farms.

I am sure that everyone reading this owns a good range of equity based funds, probably with core holdings in the major markets of the world and some tactical sattelite picks. Looking to add further diversity to this asset block is worth your attention, given that the alternatives are not attractive and the track record of complex derivatives driven absolute return funds is in the main absolute in the sense of being absolutely awful!

Is now the time right for Fintech?

Funds investing in financial businesses have been around for years, mainly owning banking, insurance company and wealth management company shares. That makes sense because financial services is a huge part of some economies like the UK and those sort of busineses are subject to very high levels of regulation, so must surely be less risky (post 2008).

But the application of technology to financial services is making as much difference as the application of steam power did to agriculture a couple of centuries back or the invention of mass production did to the availability of motor cars. Can we invest in that process of change? Of course we can and the overall shorthand is Fintech.

There are not so many financial funds on offer to retail investors but I found a few (not all will be on your favoured trading platform – that is another thing to check).

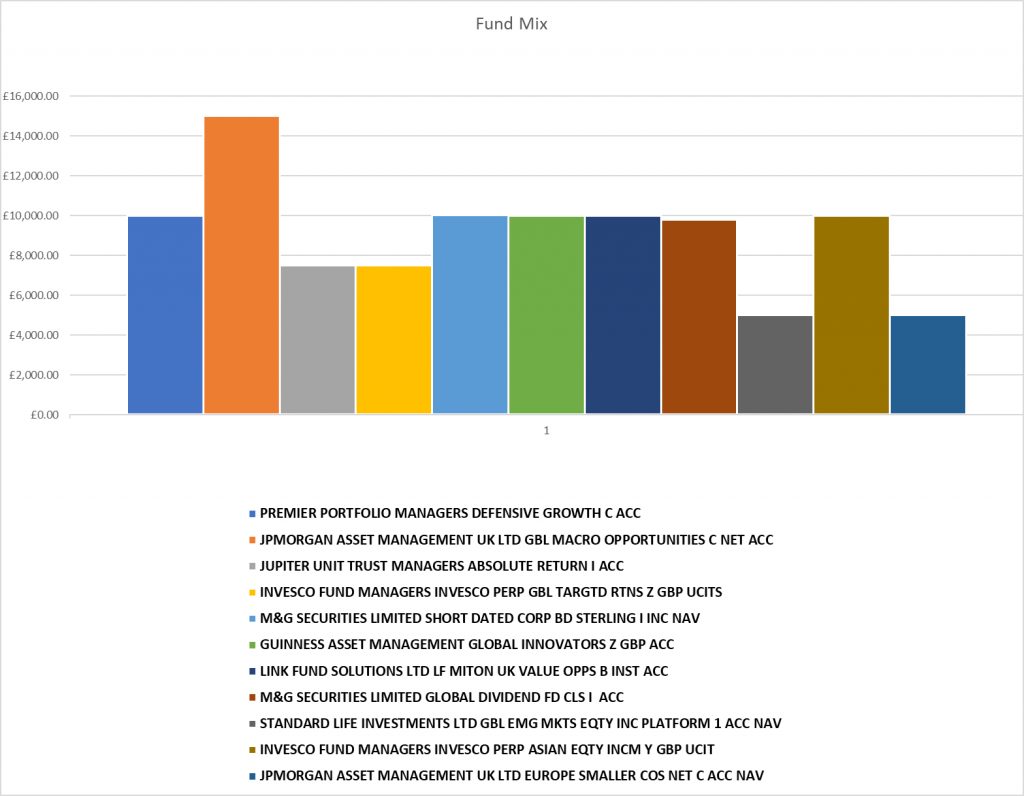
Below is a downloadable link to a Trustnet fund comparion I prepared, using the well known Fundsmith global equity fund as the benchmark, which I think is realistic. The funds I chose are really quite different in character and the correlations not too strong, bearing in mind that these are all equity funds with a global stock universe.

Example-Financial-Funds-vs-Fundsmith-1Download

As always, I am not recommending any fund and I would suggest that you take a look at the top 10 holdings, recent volatility and the typical market capitalisation of the holdings (using the Morningstar Equity Style box) because they will demonstrate quite a difference between the funds.

Jupiter actually offer 2 funds with the same manager. One is a very old fund – Financial Opportunities, the other (Financial Innovations) much newer. The innovations funds fits my idea of Fintech, but is much more risky, with the usual potential extra return and risk of heavier losses.

Im addition to the 3 in the chart, I also found these funds:

  • Jupiter Financial Opportunities – widely available UK listed, diverse large cap growth fund
  • Fidelity Global Financial Services – Luxembourg listed, mega cap bank and insurance led value fund
  • Black Rock World Financials – Luxembourg listed, similar to Fidelity with more bias to insurance companies
  • ASI Financial Equity – small UK listed fund, looks quite diverse , no named manager

There are of course Fintech ETFs (there are ETF’s for just about anything imaginable as a legitimate investment!), but I could find none offered with a UK domicile and only one with an Irish domicile, trading in US dollars and tracking the KBW NASDAQ Financial Technology Index.

Many of the real Fintech businesses are not unlike other new generation technology companies in car sharing, food delivery, internet gaming and so on. In other words, they don’t yet make profits, may be run by very charismatic people who frequently come from countries well East of London and survive on endless funding rounds. So investing in the innovative end of the financial services sector would have to be classified as high risk. But some very mainstream funds from investment houses like Baillie Gifford have been backing businesses that look pretty similar, as have many individuals with their ‘free’ trading apps. The latter may be a permanent feature of stock market pricing, so some suggest and that will help support more adventurous businesses and their share prices.

Other companies, especially those in internet shopping and money transmission services are longer established and profitable.

I repeat that I am not recommending an investment in this area to anyone, that is not my function, but I am suggesting it is an interesting area for research.

I can say, only in the interest of transparency, that I have invested in the Jupiter Financial Innovations fund. It is not uncommon for me to dip my toe into the water after completing a research exercise. Some times I wish I had not!

Filed Under: Asset Allocation, Funds, Uncategorised

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 48
  • Page 49
  • Page 50
  • Page 51
  • Page 52
  • Interim pages omitted …
  • Page 97
  • Go to Next Page »

Primary Sidebar

Recent Posts

  • Deep Dive – November 2026 (Part 2)
  • Deep Dive – November 2026 (Part 1)
  • A little foresight?
  • Mid-Month Musings – Snippets
  • Deep Dive – October 2026

Archives

Categories

  • Academic theory
  • Announcements
  • Asset Allocation
  • Basics
  • Cost of investing
  • Economics
  • Education
  • Funds
  • House rules
  • Humour
  • Innovation
  • Markets
  • Members Only
  • Monthly commentary
  • News
  • Opinion
  • Passives and Trackers
  • Politics
  • Portfolios
  • Rants
  • Research tools
  • Site Content
  • Sustainability/ESG
  • Trading
  • Uncategorised