Markets
Deep Dive – February 2025
Trump 2 – a different and personal take on the implications
So far…
At this early stage of the new US President’s term of office, it is not possible to make any reliable predictions about the global macro economic impact beyond examining the potential threats, which I have already done in a number of ways, as have many, many other commentators.
I will this month offer what is absolutely only an opinion, based on my personal view of the world, so this piece is not claimed to be educational. Feel free to disagree with me: I will be satisfied if I have prompted you to think about the situation in a new way or added an angle to your existing assessment.
YAP – snippets
Firstly an apology if you tried to view my latest video on YouTube yesterday and could not.
I had set it for a midnight release but did not check in which time zone that midnight was. I am still getting used to using a video server and all that entails.
Because it worked for me immediately, I did not mention that fact in the release announcement. Sorry if you wasted time trying to view it. It is a public video, so you don’t need any password or login to access it from the link. However, if you use YouTube rarely, please do ensure that your device has the up-to-date version running.

Of more interest is some data just published by Morningstar, below:
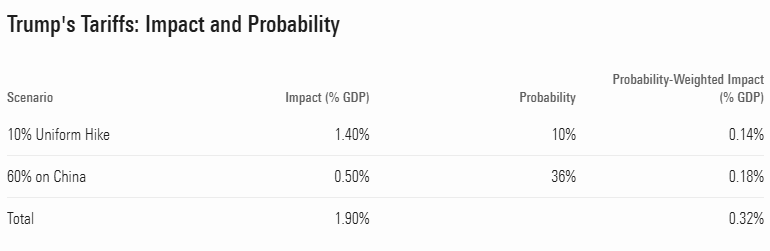
The only thing I would add is that my personal intuitive assessment of the probability of Morningstar being right is only 50%!
YAP – a momentous day
I have written with some trepidation about the potential consequences that will result from Trump 2.0. The global macro-economic outcomes of some of the promised policy actions could be dramatic.
Markets seem to have taken an optimistic turn in the last few days. That probably means that participants are betting that there is more bluster than real intent in the bombast that has always characterised Donald Trump’s attempts at global politics.
I am in no way convinced that this optimism is justified but am happy to look at better numbers in my portfolio valuations, of course!
I am not proposing that the most damaging or bizarre of the touted policies will, or will not, be actioned. I don’t really think we will know that for a while, although some actions are promised even for today.
It often takes years for some major political missteps to impact economies and financial markets permanently – Brexit is a great example of that, although I know not everyone agrees with my view that for Britain’s financial markets it was a mistake. Only the most partisan could now argue that there was a boost to the UK’s global status as a financial centre in the years since Brexit. Other consequences are now apparent, although not much publicised.
I personally remain very nervous about the immediate future consequences of the 47th presidency of the USA. I think there are a few likely scenarios, but it is pointless speculating ahead of the inauguration.
Rather better to keep a close eye on the news and market reactions to the news as it emerges, not forgetting to try and work out the longer-term consequences. I will do my best to add interpretation as soon as I have an opinion.
YAP – 2025 as seen from New York
I receive a daily news feed on markets from the Dealbook team at the New York Times. I find this useful as we all know that what happens in the US stock markets is highly relevant data in interpreting the global macro-economic climate and overall financial risk.
The New York team leader Andrew Ross Sorkin recently published his thoughts on what might happen in 2025. Now pundits there are a plenty, but this author has contacts at the very highest levels of US business, so you might be interested in his thoughts as context. I have picked the points I thought most relevant to UK-based retail investors. My own touch of flavour is added.
YAP – new video
Below is a link to a new video in which I comment on the implications of Trump 2.0 as far as they can be judged at this early stage. My comments are partly based on a recent webinar given by Steve Bell, the Chief Economist (EMEA) for CT.