• Skip to main content
  • Skip to primary sidebar
  • About This Website
    • A polite reminder
  • How To
    • Use this website and benefit from the subscription option
    • Pick a financial adviser
    • Ensure your investment adviser is delivering good value
    • Get expert help with running your own portfolio
    • Pick a ‘tax wrapper’
    • Pick a Trading Platform
    • Diversify a portfolio in today’s world
    • Invest in line with your conscience
    • Research (screen for) a specific fund requirement (m)
    • Pick a fund for the future or how to be a contrarian (m)
    • Find the ‘next best thing’ and make rational sell decisions (fund switching) (m)
    • Time investment sales (skim profits) (m)
    • Interpret a Morningstar X-Ray (m)
    • Use Trustnet for Research (m)
    • How to review a neglected portfolio when the world has moved on (m)
  • *Important Information*
  • Real World
    • A Frank Introduction to Investing
    • Costs
    • Investment Risk – Your Starter For 10
    • How are advisers fees worked out?
    • 10+ top tips for investors
    • An actual portfolio review (m)
    • Benchmarks – a thorny subject
    • Disinvestment from fossil fuel businesses – are there better options?
  • Tales of the Unexpected
    • Lola
    • Round and Round the Mulberry Bush
    • FOMO (Fear of Missing Out) and the lazy mind.
    • Property Development Schemes
  • For More Experienced Investors
  • Glossary with a Difference
  • Member Only Content (M)
    • Example of simple cash flow planner (m)
    • Long Reads
      • What is market shorting and is it a bad thing?
      • How to conduct a periodic portfolio review (m)
      • Investing without management (passively) – a better way? (m)
  • Portfolios and Funds (m)
    • Lessons in Portfolio Construction and Maintenance – Introduction
      • High Level Asset Allocation
      • Selecting Funds
      • Cash Flow and Tax Issues in Portfolio Construction
      • Setting Objectives and Understanding Risks
      • A suggested portfolio for Alex Bright
  • Multi Asset Academy (m)
    • Some basic basics
    • Who are Vanguard?
    • Are multi-asset funds expensive?
    • Cheap and cheerful?
    • Its all about asset allocation, but…
    • Myth and misunderstandings
    • Taking money out of multi asset funds – the pros and cons
    • Distribution funds – the forerunner of multi asset investing?
    • DIY Multi Asset – adding risk controls
    • Benchmark Fog
  • Member Login
  • Logout

Its Not Harry

Comment and opinion for retail investors in the UK

Asset Allocation

Watching Brief – July 2021

1st July 2021 by Mark Potter Leave a Comment

Pottering About

I have written before about my judgement that equity markets were overvalued at the end of 2019 never really getting tested because the advent of Covid-19 and the response of global governments (ie a huge stimulus of ‘free’ money) created a set of conditions that were way beyond the normal market cycle. 

I have argued since that the flow of cheap money and one other factor that I have repeatedly mentioned, the arrival of novice retail traders with new technology at their disposal, has been propelling valuations along for equity shares and some new asset classes like crypto ‘currencies’ and their plethora of proxies.

I think we have seen enough since March 2020 to come to some new conclusions.

So, how is your 2021?

Half yearly pause for thought

As inflation rears its head and there is talk of rising interest rates – see next article for some analysis of the direct impact of this – and the Covid crisis is becoming normalised in Western economies, perhaps we should consider the Covid deflection almost fully worked through?  Certainly, we must be close to the end of ‘spend, invest and be merry for tomorrow never comes’ era for governments.
You need to be logged in to view the rest of the content. Please Log In. Not a Member? Join Us

Filed Under: Asset Allocation, Markets, Members Only, Monthly commentary, Passives and Trackers

Midweek Musings – What Use Are Alternatives Funds?

5th May 2021 by Mark Potter Leave a Comment

Introduction

Portfolio theory from the late 20th century suggested that one could mitigate the volatility risk of owning equities by buying fixed income stocks (bonds). Some investors would add real estate, usually commercial property, as well. That basic model had long been modified in the institutional investment market by the use of hedging techniques and the investment firms that market products to retail investors have for some 30 years now been offering ‘tamer’ versions of hedge fund investing in the form of absolute return (AR) funds. That phrase is rather UK centric and in the USA a more common classification is ‘alternatives’. Morningstar has pigeon holed funds into a range of alternative categories.

Some changes in Morningstar categories for Alternatives

That firm recently reviewed the classification against a background of general consensus that many funds thus described were not really doing what they promised. I recently listened to a presentation that explained what they had discovered in Europe and the UK and what they were going to do about it.

Here are the main points as I noted them:

  • AR or alternative funds are complex and many have disappointed
  • New categories would better describe the way such funds are supposed to work
  • In the past there has been a very high attrition rate as funds have failed and closed (or rarely, used one technique so successfully that it could not be repeated!). More funds closed than opened in 2019 and 2020 and only one in 5 funds in all their current alternative categories is more than 10 years old.
  • Some funds (for example many listed as long/short) are not actually being run any differently to mainstream equity funds, so should be recategorised in the relevant equity category. This I had observed years ago with the Newton Real Return fund, which was presented as an absolute return fund but was really just a tactical international equity fund.
  • There has been inconsistency at Morningstar in the categorisation of such funds across global markets. I think that UK investors would have maybe been using the Investment Association category (Targeted Absolute Return) anyway, so would not have been overly concerned about Morningstar’s global policy. That IA category also includes a mixed bag and should be treated with caution, by the way.
  • They are taking action that puts funds of a similar style together and with simpler definitions, where possible.
  • Their overall definition of what makes a fund ‘alternative’ now takes on board the concept of expanding portfolio diversity or eliminating dominant risk factors in traditional markets, having low correlation but some flexibility. One might guess that is what the average retail investor understands hedging to mean, so great!
  • A new category addition will allow for some managers using currency as a specific risk mangement technique
Researching alternatives should be a more straighforward process from now on.

Inplications for us

I think this is good news. I have explained to investors how difficult it is to identify the different styles in funds that are marketed as useful for diversification and risk control.

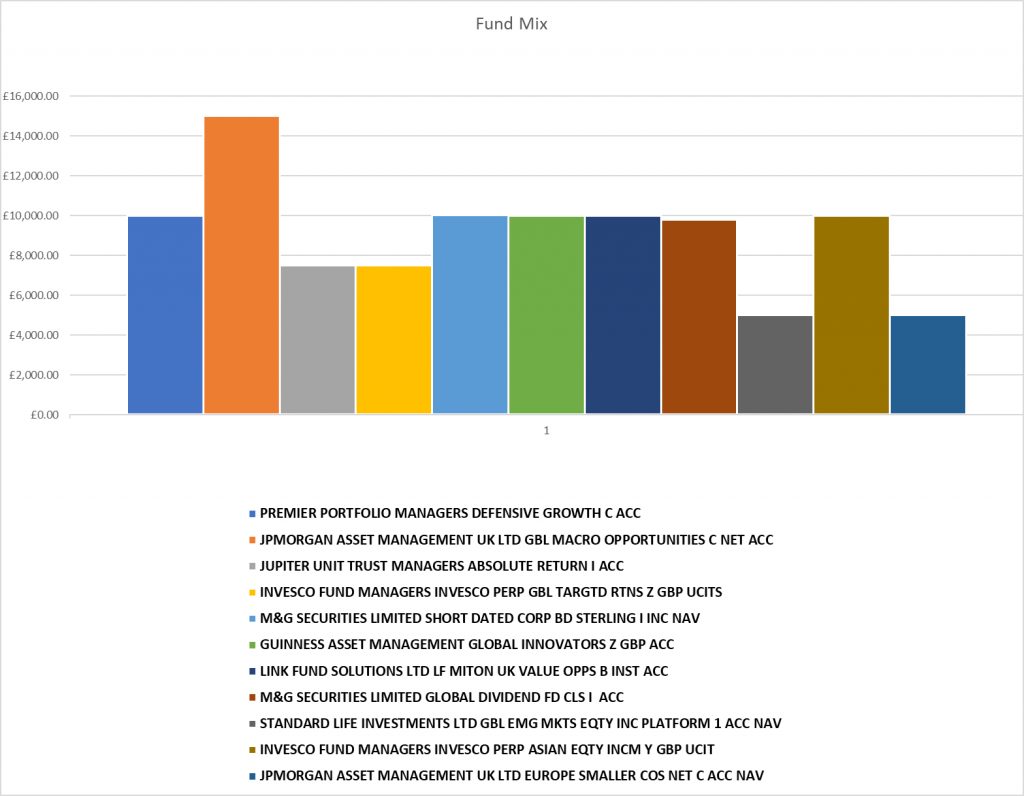
I have had to tell people that some products in the markets are using techniques like selecting non correlated global macro themes that are not recognised as Absolute Return objectives and so those funds are hard to research. The JP Morgan Global Macro Opportunities fund which I have owned for many years is one such.

The new categories will bring together funds like that (Macro Strategy) and assist our research. Moving funds that were pretending to be clever at handling risk back into groups with general managed equity funds will get rid of some funds that were not doing what they said on the tin!

Filed Under: Asset Allocation, Monthly commentary, Portfolios

Midweek Musings – 6–8–9, time to get in line!

28th April 2021 by Mark Potter Leave a Comment

Introduction

This week’s post is shortish because I will publish a fuller subscriber only Watching Brief over the weekend or early next week.

The title refers to the categorisation of funds in Sustainability terms under the EU’s recently in force SFDR sustainable finance directive.  Although the UK is not of course in the EU, all fund managers wanting to market funds in Europe (which includes all the large UK fund managers) will comply with the rules.

The categories

As usual with EU policy documents, the rules run to many pages, but for our purposes, we only really need to get used to the 3 ‘articles’ or categories of fund referenced in the title.

  • Category 6 is general retail funds such as we might purchase
  • Category 8 is funds that promote environmental or social characteristics (light green)
  • Category 9 is funds that have a specific sustainable investment objective (darker green, but not necessarily ethical)

How are funds lining up so far?

Actually, we are looking for numbers not letters!

Morningstar have published some early data from about half the funds with domicile in Luxembourg, the favourite base for non-European fund managers to use for selling into Europe, on how funds are coming out as the process gets under way. 

It is probably a good idea to keep in mind that when any new rules are published, they are subject to varying intepretations, especially when talking about categorisations (think of Covid-19 death rates).  So I would assume that some fund groups are going to be more liberal with the rules and others more literal, or pedantic. 

It is no surprise that European groups as opposed to UK or US fund businesses are in the main showing a higher proportion of category 8 and 9 funds because it is well known that European investors have been more in favour of ESG filters for a while and one might also speculate that the European fund managers are a little cuter at tuning their documentation to fit in with EU rules – just my idea!

On this early data funds classified as Article 8 or 9 represent 21% of European funds by number and 25% of European assets. This data is extrapolated by Morningstar, rather prematurely in my opinion, to suggest that the ESG funds market in Europe is worth EUR 2,5 trillion. Not a trifling sum even in these days of money sloshing around everwhere.

In case you are interested the French firms Amundi and BNP Paribas have the highest number of funds in 8 or 9, well into the hundreds. The UK’s top player was Legal & General with around 50 funds and even the mighty Fidelity International only has just above 50.

When it comes to actual money invested, unsurprisingly, Nordic and Dutch asset managers fill all the top spaces. SEB, a Swedish bank that operates in my region classified 95% of its assets in categories 8 and 9. The bank I personally use, also Swedish, too small as a fund manager to make this survey, has 100% of its funds ESG assessed as far as I can tell – the facts sheets always include a significant ESG commentary.

Does this matter to us?

I think it does. I have been pretty sure for some time that the global enthusiasm for sticking a ‘sustainable’ label on investments and booing loudly everything that superficially is not sustainable will be the biggest driver of investment fund flows for years to come. So even if you are more sceptical than me about the quality of the labelling on ESG funds, it makes sense to to at least keep up with this bandwagon, even if you don’t want to jump on.

Filed Under: Asset Allocation, Funds, Monthly commentary, Politics

Midweek Musings – Home Advantage?

17th March 2021 by Mark Potter Leave a Comment

My theme this week is the impact of currency fluctuations on portfolio returns. I have been aware of this important factor since I first started learning about investments. I can’t predict currency movements in the short term (a whole industry thrives on playing that game), but I think anyone can assess relative currency risk.

Key principles

My bureau de change!

Let’s start with some basics. What makes a currency more or less valuable? Here are some of the main reasons:

  • Security – how capable is the country issuing the currency of sustaining its relative value? A world superpower in economic (not military) terms with open, efficient and highly liquid markets will get the most respect. The USA, UK, Eurozone or Japan offer what are called the ‘reserve’ currencies. China wants to join that list.
  • Politics – is the government behind the currency respected as prudent and unlikely to borrow beyond the country’s means. Such borrowing might come in the form of ‘printing’ money and if there is more of a currency around, its value may well fall. A reserve currency country has more scope to extend its currency base, but not indefinitely
  • Interest rates and their anticipated direction (highly significant) – there are always people and corporations and even governments with surplus cash to deposit for short periods, even just overnight. Naturally, that cash gets placed where interest rates are highest and to deposit the cash, you probably need to have it in the relevant currency. So there is demand for currencies issued by countries with higher interest rates on offer. By the way, this fact is the main driver in the price of Bitcoin, which is non-national commodity asset that can be substituted for currency.
  • Asset prices in the issuing country – if a country has been having a hard time and is thought to have turned a corner, then richer market players will look to pick up assets of all sorts – shares, whole businesses, properties and so on – at bargain prices. To buy those assets they need local currency, so demand will increase. The opposite applies when the perceived prospects for a country turn negative, or just become muddied, which is why Sterling fell sharply after the Brexit vote.

How does that impact on our investment decisions?

How do fluctuations in currency impact investors, in a direct sense?

Most of the time, we will invest in funds, ETFs or shares priced in the currency of the country in which they are issued. Some funds have “hedged’ share classes, but hedging costs money and it not 100% effective, so has not proved popular with retail investors. So if there is a change in the relative value of the currency in which our investment is issued, the value in our investment report, which is in Sterling, will change, irrespective of any other factor.

Imagine we bought GBP1000 of units in a fund that invested only in the USA. Overnight, the value of the fund’s investments goes up while the US stock market is working by 1%. So our investments should be worth GPB1010 next day. Actually, that will rarely be the case.

If the USD dollar went up 0.5% relative to Sterling, our gain would be 1.5% (GBP1015). If it fell 0.5%, our gain will reduce to 0.5% (GBP1005).

Currency values fluctuate by small amounts daily most of the time, but there are exceptions. Generally, there are trends in relative valuation and sometimes (maybe rarely), one can take a view that there is high probability of one currency going up or down relative to another because one is aware of the impact of the factors detailed above.

For example, it was highly likely that Sterling would depreciate between the date of the Brexit referendum vote and the outcome of negotiations and so there was little currency risk for UK investors buying overseas funds. In fact there was a good case for owning no UK investments at all during that period, because there was no direct currency upside in them.

Note the changes in a currency’s relative value will impact on trade and corporate profits, so there is more to understand on this matter, but that is not something we need to cover here.

Sterling as the Phoenix

Anyone who looks at their portfolio regularly will have noticed weaker performance in terms of valuation numbers from global equity funds over recent weeks. This is mainy because Sterling has been appreciating steadily. The UK Pound Sterling index is a measure against a weighted basket of other currencies and it is up from about 127 to 138 since 6 months ago, nearly 9%. That is quite a headwind for valuations of stocks listed in other currencies.

Why is Sterling going up so steadily? There are multiple reasons which fit in with my criteria above.

Should we be carrying the torch for British businesses?

The final ‘doing’ of Brexit has reduced political risk, even if there is no economic boom yet. The success of the vaccination programme in the UK has been taken as implying an early re-opening of the British economy.

Interest rates rising is not likely to be a baked in expectation yet, so that is one NOT yet applicable factor. But there may be a growing anticipation of higher inflation, which would be followed by higher interest rates – the data points that way.

I suggest that main reason is that UK assets have become outstandingly cheap and overseas investors, slighly jaded with the big US tech firms and worried about the huge cash flows into non-profitable new ventures listed on the NASDAQ, are thinking about buying some old fashioned ‘value’ businesses that sell stuff all over the world, make profits and pay dividends (and as an aside, may be ripe for takeover). So I guess that an inflow of foreign capital is one driver behind the appreciation of Sterling.

Now if a lot of other people want to buy UK company shares and our profits from overseas investments are being cut back by a possibly long running increase in the value of Sterling, maybe we should be looking close to home if we are keen on getting some assets at good prices with no currency risk?

That has already quite a reversal of tactics for me. But as J M Keynes suggested, when the facts change, you need to change your mind.

I think UK investments, carefully researched with some of the contrarian techniques I have explained before, would be a logical inclusion on any shopping list for those wanting to put money into the market or bank some profits from their momentum led tech funds. And there will be no direct currency risk!

Filed Under: Asset Allocation, Monthly commentary, Uncategorised

Midweek Musings – Let’s get started!

10th March 2021 by Mark Potter 2 Comments

It seems to be ‘de rigeur’ to use the phrase ‘Let’s get started’ or similar at the start of a YouTube video and who am I to fight fashion?

This new format will on occasions cover a little more ground than its predecessor but it is still my ambition that you can take it in over a leisurely cup of coffee. More detailed analysis will appear in the subscriber only monthly WAtching Brief, and if requested, by the addition of longer reads to the main permanent site content. There will be plenty of fund specific content to give you ideas to follow up if they are of interest.

I had decided to omit my usual graphics too, to use the minimum of screen real estate because I expect some people will read this on their smartphone, but if that disappoints anyone, please comment as usual. Feedback is welcome and acted upon. The initial reaction I got was that the graphics helped with readability, so I added some in! I will adapt as appropraite if there is more feedback.

This weeks theme – diversifying your equity holdings. How about Fintech?

Inflation reborn?

As I have already explained in recent posts, the yield on US Treasuries has been slowly climbing, such that the long end of the yield curve is around 1.5%. This has been happening for about 6 months but a whole swathe of data on inflation has made market participants begin to accept that higher interest rates are coming in the medium term. Central bankers are doing their best to suggest that they are in no hurry to raise rates, but some of the inflation numbers are striking.

I saw a presentation earlier this week, a European focused one, where data was presented showing raw material prices increasing annually now at over 3.5% and for some minerals, much faster than that. Food prices are also moving up sharply and most readers will already know about the huge jump in the cost of renting shipping containers. Add to that a big jump in crude oil pices and a massive overhang of consumer savings on deposit at banks, likely waiting to be spent as soon as the world opens up to travel and shopping, and predictions of significant price inflation seem logical.

Asset class selection

As most of my readers will know, rising interest rates are bad news for fixed income investors, because the value of securities already issued moves in the opposite direction to interest rates. Precious metals, if not in demand in industry or for retail consumption, will also lose value because they have no yield. Deposits of cash will earn better returns but initially that is almost bound to be below the rate of inflation.

This classic model of a lower risk diversified portfolio from around 3 years back now looks seriously in need of revision, although many components will have done well enough

Of the major asset classes. one is left with equities and physical property. The latter is an asset that could do well if the actual properties are carefully selected but most mature funds will own too many retail shops and conventional office blocks and not enough logistics warehouses and server farms.

I am sure that everyone reading this owns a good range of equity based funds, probably with core holdings in the major markets of the world and some tactical sattelite picks. Looking to add further diversity to this asset block is worth your attention, given that the alternatives are not attractive and the track record of complex derivatives driven absolute return funds is in the main absolute in the sense of being absolutely awful!

Is now the time right for Fintech?

Funds investing in financial businesses have been around for years, mainly owning banking, insurance company and wealth management company shares. That makes sense because financial services is a huge part of some economies like the UK and those sort of busineses are subject to very high levels of regulation, so must surely be less risky (post 2008).

But the application of technology to financial services is making as much difference as the application of steam power did to agriculture a couple of centuries back or the invention of mass production did to the availability of motor cars. Can we invest in that process of change? Of course we can and the overall shorthand is Fintech.

There are not so many financial funds on offer to retail investors but I found a few (not all will be on your favoured trading platform – that is another thing to check).

Below is a downloadable link to a Trustnet fund comparion I prepared, using the well known Fundsmith global equity fund as the benchmark, which I think is realistic. The funds I chose are really quite different in character and the correlations not too strong, bearing in mind that these are all equity funds with a global stock universe.

Example-Financial-Funds-vs-Fundsmith-1Download

As always, I am not recommending any fund and I would suggest that you take a look at the top 10 holdings, recent volatility and the typical market capitalisation of the holdings (using the Morningstar Equity Style box) because they will demonstrate quite a difference between the funds.

Jupiter actually offer 2 funds with the same manager. One is a very old fund – Financial Opportunities, the other (Financial Innovations) much newer. The innovations funds fits my idea of Fintech, but is much more risky, with the usual potential extra return and risk of heavier losses.

Im addition to the 3 in the chart, I also found these funds:

  • Jupiter Financial Opportunities – widely available UK listed, diverse large cap growth fund
  • Fidelity Global Financial Services – Luxembourg listed, mega cap bank and insurance led value fund
  • Black Rock World Financials – Luxembourg listed, similar to Fidelity with more bias to insurance companies
  • ASI Financial Equity – small UK listed fund, looks quite diverse , no named manager

There are of course Fintech ETFs (there are ETF’s for just about anything imaginable as a legitimate investment!), but I could find none offered with a UK domicile and only one with an Irish domicile, trading in US dollars and tracking the KBW NASDAQ Financial Technology Index.

Many of the real Fintech businesses are not unlike other new generation technology companies in car sharing, food delivery, internet gaming and so on. In other words, they don’t yet make profits, may be run by very charismatic people who frequently come from countries well East of London and survive on endless funding rounds. So investing in the innovative end of the financial services sector would have to be classified as high risk. But some very mainstream funds from investment houses like Baillie Gifford have been backing businesses that look pretty similar, as have many individuals with their ‘free’ trading apps. The latter may be a permanent feature of stock market pricing, so some suggest and that will help support more adventurous businesses and their share prices.

Other companies, especially those in internet shopping and money transmission services are longer established and profitable.

I repeat that I am not recommending an investment in this area to anyone, that is not my function, but I am suggesting it is an interesting area for research.

I can say, only in the interest of transparency, that I have invested in the Jupiter Financial Innovations fund. It is not uncommon for me to dip my toe into the water after completing a research exercise. Some times I wish I had not!

Filed Under: Asset Allocation, Funds, Uncategorised

Monday Mashup – gold: hold or fold?

22nd February 2021 by Mark Potter Leave a Comment

The price of gold bullion has declined steadily in US dollar terms for some months since its peak last Summer. A decline in the value of the dollar relative to Sterling will have added an extra loss for investors reading this post, and that includes me!

Readers who own gold bullion may therefore be asking the question in the title.

Why own gold and what about Bitcoin?

I own gold bullion because some 9 months or so back, I wanted to have an asset that was not correlated with global equities and would retain value if the pandemic got totally out of control. Fixed income and physical property investments did not look like offering much value then (and they still don’t) and there was obvious demand for gold.

Gold is a commodity and generally commodities (which include cryptocurrencies like Bitcoin) don’t pay an income and won’t be worth more because an enterprise does well. The price is directly and only determined by supply and demand.

Because high value minerals like gold and high complexity assets like Bitcoin are hard to mine and bring to the market (for completely different reasons of course), the supply side is known to be limited. So in making an investment bet on such assets, one is always taking a view on the demand side of the equation.

Money ‘rotates’ around asset classes over time

What’s changed?

This is the key to working out the completely opposite path of returns for gold and Bitcoin over the last few months. We have less demand for gold (more on that later) and more demand for Bitcoin.

The latter has a new champion with a big fan base in the form of Tesla’s Elon Musk, who has invested shareholders’ cash into Bitcoin in a big way.

The other reasons for Bitcoin demand rising I can only guess, but I would suggest it is possibly our old friend ‘herd mentality’, plus a bit more of a reported positive attitude from blue chip investment houses, although not reserve banks!

The reduction in demand for gold can be attributed to several factors. The main one is that the pandemic risk is thought to be much reduced, so avoiding national ‘fiat’ currencies is less important. Another is that interest rates on US treasuries are slowly rising, implying a market expectation of inflation and/or a slowing of US government money printing in the mid-term – surely inevitable.

Although gold is an excellent inflation proof asset in the long run, it has no income yield. When risk free (as is the convention) assets like US treasuries also have no yield and could lose capital value on a rate rise, gold looks attractive.

When interest yields pick up, the short term investor would rather have the income now than the inflation proofing later, so money rotates away from gold to lower risk (now improved) yield assets.

If such investors exected a sharp rise in interest rates, they would hesitate to buy the fixed income assets, because of the anticipated capital loss, so the markets are telling us that they only expect gentle rate rises over a long period. There is some debate about that, but the collective psychology of the market is always right for the time being!

So, what to do?

One could take the view that gold is a useful core portfolio asset, offering security and diversity and over the long term is both a volatility damper because of the low or even inverse correlation with global equities, and it will serve as an inflation hedge. In that case, it makes sense to keep a modest asset weighting.

Should you invest in crypto currencies instead?

I am not qualified to add to the view of regulators and cental bankers who suggest that although these new assets are very similar in character to precious metals, the way they are traded is probably not unlike the trading of the shiny stuff back in the 19th century at the ‘gold rush’ sites. Some people made fortunes, some went on to control large parts of the market and most people were financially wiped out. In other words, retail investors ought to stay away for now.

Another point of view would be that the vaccine programmes are going well, Covid-19 infections are coming down, there will be no real double dip recession and instead a consumer boom will drive up prices and in time interest rates. That proposition would imply that owning equities, even though they are currently expensive in many markets, or even well selected property assets, is a better tactical (ie short term) option and both fixed income and conventional commodities are not likely to make money.

If you are of the latter more optimistic frame of mind, you ought to think about controlling volatility in other ways within an equity portfolio. Investing in infrastructure is something that comes to mind, given that we expect high levels of government spending, or adding heavier weightings to healthcare funds, perhaps? I am not sure I know the full answer at the moment.

I did it my way?

As for me…..

You might expect me to tell you what I will be doing.

The answer is that I will not add to my physical gold holdings and as I have cash to put into the markets when I see opportunities, the relative weighting will go down.

Aside from that, I personally see no case for selling out, but my circumstances and portfolio will not be the same as yours, dear reader, so if you own gold, you need to make your own mind up!

I hope these comments help.

Filed Under: Asset Allocation, Monthly commentary, Portfolios

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 8
  • Page 9
  • Page 10
  • Page 11
  • Page 12
  • Interim pages omitted …
  • Page 14
  • Go to Next Page »

Primary Sidebar

Recent Posts

  • Mid-month Musings – September 2026
  • Deep Dive – September 2026
  • Mid Month Musings with Mark (not me!)
  • Thank You
  • Deep Dive – August 2026

Archives

Categories

  • Academic theory
  • Announcements
  • Asset Allocation
  • Basics
  • Cost of investing
  • Economics
  • Education
  • Funds
  • House rules
  • Humour
  • Innovation
  • Markets
  • Members Only
  • Monthly commentary
  • News
  • Opinion
  • Passives and Trackers
  • Politics
  • Portfolios
  • Rants
  • Research tools
  • Site Content
  • Sustainability/ESG
  • Trading
  • Uncategorised