• Skip to main content
  • Skip to primary sidebar
  • About This Website
    • A polite reminder
  • How To
    • Use this website and benefit from the subscription option
    • Pick a financial adviser
    • Ensure your investment adviser is delivering good value
    • Get expert help with running your own portfolio
    • Pick a ‘tax wrapper’
    • Pick a Trading Platform
    • Diversify a portfolio in today’s world
    • Invest in line with your conscience
    • Research (screen for) a specific fund requirement (m)
    • Pick a fund for the future or how to be a contrarian (m)
    • Find the ‘next best thing’ and make rational sell decisions (fund switching) (m)
    • Time investment sales (skim profits) (m)
    • Interpret a Morningstar X-Ray (m)
    • Use Trustnet for Research (m)
    • How to review a neglected portfolio when the world has moved on (m)
  • *Important Information*
  • Real World
    • A Frank Introduction to Investing
    • Costs
    • Investment Risk – Your Starter For 10
    • How are advisers fees worked out?
    • 10+ top tips for investors
    • An actual portfolio review (m)
    • Benchmarks – a thorny subject
    • Disinvestment from fossil fuel businesses – are there better options?
  • Tales of the Unexpected
    • Lola
    • Round and Round the Mulberry Bush
    • FOMO (Fear of Missing Out) and the lazy mind.
    • Property Development Schemes
  • For More Experienced Investors
  • Glossary with a Difference
  • Member Only Content (M)
    • Example of simple cash flow planner (m)
    • Long Reads
      • What is market shorting and is it a bad thing?
      • How to conduct a periodic portfolio review (m)
      • Investing without management (passively) – a better way? (m)
  • Portfolios and Funds (m)
    • Lessons in Portfolio Construction and Maintenance – Introduction
      • High Level Asset Allocation
      • Selecting Funds
      • Cash Flow and Tax Issues in Portfolio Construction
      • Setting Objectives and Understanding Risks
      • A suggested portfolio for Alex Bright
  • Multi Asset Academy (m)
    • Some basic basics
    • Who are Vanguard?
    • Are multi-asset funds expensive?
    • Cheap and cheerful?
    • Its all about asset allocation, but…
    • Myth and misunderstandings
    • Taking money out of multi asset funds – the pros and cons
    • Distribution funds – the forerunner of multi asset investing?
    • DIY Multi Asset – adding risk controls
    • Benchmark Fog
  • Member Login
  • Logout

Its Not Harry

Comment and opinion for retail investors in the UK

Markets

Monday mashup – a quiet Easter?

13th April 2020 by Mark Potter Leave a Comment

If you are like me, you will have spent Easter mostly at home with maybe a short trip or two to the supermarket or a walk or bike ride, (with a mask on?) for permitted exercise. In the meantime, stock markets have been closed and the tone of the news about the pandemic has taken a distinct turn towards looking for the end of lockdowns (at least in parts of Europe) and ‘exit strategies’.

Of the latter, I suspect there are few that are complete and unsurprisingly much is I think being made up as we go along.

It’s all going to be fine … (said Donald?)

It was clear over the course of last week that investors in enough numbers to generate a sharp jump up in prices were reading the news of a slow down in virus case number growth (in the European hotspots) as heralding the end of the crisis.
The sun is coming out from the clouds and we will soon be back to ever rising stock markets…or will we?

Either that or they just think that the money being thrown at the problem by global powers is going to feed through to company profits without so much as a trading statement on the way!

I have some problems believing that this turn around is based on solid foundations.

A Spanish government minister was quoting as saying that ‘the fire is coming under control’. That is good news but it does not mean that the fire is still not slowly burning away causing continuous economic destruction, never mind the human cost.

My recall of images of places after fires have been brought under control is of burnt out buildings, black vestiges of landscape and car shells on ther way to the scrap yard.

What seems to be working

This link will I hope work for most readers

https://aatishb.com/covidtrends/?location=Lithuania&location=Netherlands&location=South+Korea&location=Sweden&location=Taiwan

The graph shows the rate of growth in new Covid-19 cases in several countries. I have omitted the US and UK because the lines are virtually straight (ie no improvement). You can play with the data, adding or removing countries as you wish.

The countries that knew how to deal with a virus because they had experience of SARS have got the situation under control quickly, with minimum economic damage. Lithuania, the country where I live, being small and able to more easily enforce and monitor a lockdown policy has also started to get improving results – the graph for New Zealand is almost identical. Other countries that made quick decisions on testing and contact tracing are doing well

The lines for Sweden and the Netherlands are added because they took a more liberal view and did not impose lockdowns. Yet. I see that as evidence that they made the wrong calls. Having very socially liberal democracies is like a democratic management style in business, not so good in a crisis.

I provide this data as a useable set because I conclude from a much bigger set of information that the virus is coming under control in some places but will not come under control in countries that are not serious about taking the right measures, be they lockdowns, testing and contact tracing and so on.

Note that I make no comment about vaccinations and effective treatments because in spite of extensive reading, I find nothing to suggest either are round the corner. I also recognise that the virus may be seasonal, if we are lucky.

This line of thinking leaves me extremely concerned about the progress of the disease in the USA, by far the largest stock market in the world and a major source of investor wealth over many decades.

A new driver for markets

There is a new way of looking at stock market direction that takes account of the massive flows into passive or index tracking funds over recent years. There was a fear that such funds might struggle to remain ‘liquid’ in a severe market correction, but so far that difficulty has not happened. Some have become dislocated in pricing terms from the indices they were supposed to be tracking, but this has only been temporary.

Of course, a simple tracker will have been exposed to the full volatility of the index it is tracking and may have lost more money than a managed fund covering that range of shares or bonds. But the multi asset passive funds have generally lost only a little more than managed funds in their peer group and still retain their long term performance advantage, partly a consequence of their low fees.
As passive fund investing has become more sophisticated, I have come around to seeing it as a useful option in the investor’s toolkit.

It seems to me that nothing that has happened over the last few weeks is going to permanently dent the enthusiasm of investors for this sort of investment product and that has consequences for the trading patterns of the markets.

If there are huge sums in funds run by computer algorithms, that money is bound to follow market changes (because the algorithms are programmed to do that).

If for example, traders who are still making decisions place enough orders for Apple shares to push the price up a bit, vast sums of money will potentially flow into Apple shares from passive fund algorithms looking to rebalance their asset mixes, or set up to react to ‘trigger’ information.

It is not possible to easily work out the precise impact of the passive funds – it seems to me to be the sort of subject someone might get a Nobel prize for – but there are many commentators who believe it is a significant contributor to market direction. It may add to volatility. It certainly makes ‘momentum’ a factor to allow for in making decisions.

What is perhaps most worrying is that it looks like passive investing could be the trend that destroys ‘value’ investing. If no-one really sees a case for valuing companies on the potential future growth of profits and dividends from a good value (ie cheap) base point, then all sorts of classic investment models will fail.

If you want to re-invest, where to look?

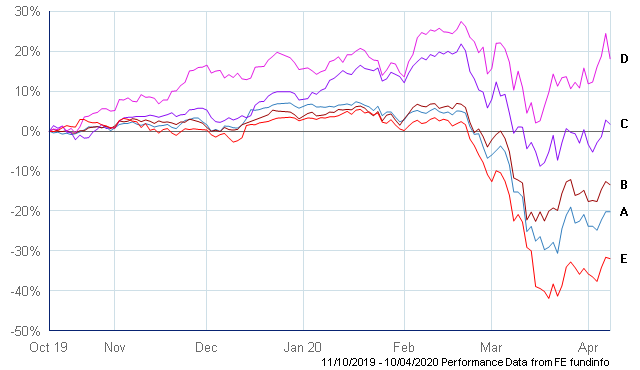
Funds-examples-0420Download

If you look at the chart offered here for download you will see a wide variety of recent returns, although the ‘systemic’ risk shows in all the lines. This is just a sample to make a point

The ‘value’ fund shown (e) – the well known and once much loved M&G Recovery fund has seen a severe loss of value. Biotech and IT company biased funds (d and c) have done much better – no surprise there. The UK and Europe (a and b) and for that matter most global markets only measured geographically have seen similar declines, but here there are differences because of currency and I think because of Covid-19 impact, although I have no evidence to prove that.

So, let’s all buy the most sold off fund? I don’t think so, although that would have worked in the past. We need to think about what will happen to markets in the future, based on what we know now, which is why I have presented the analysis above. The investment world may have been through a permanent change.

Maybe the more expensive (in relative terms) bio-tech stocks are going to be favoured because of rather simplistic decision making by investors feeding into biotech ETFs and other low cost tracker funds. It might be that there is actually no improvement in the success or profitability of the shares making up some bio-tech index but the wall of money that might be heading there will push up prices anyway.

What do you think?

I can’t say that at this moment I know the answer the question posed in the heading, but I know what I am keeping an eye on! I am happy to explore these ideas with readers in more detail if it will help them in their research and asset allocation work.

PS

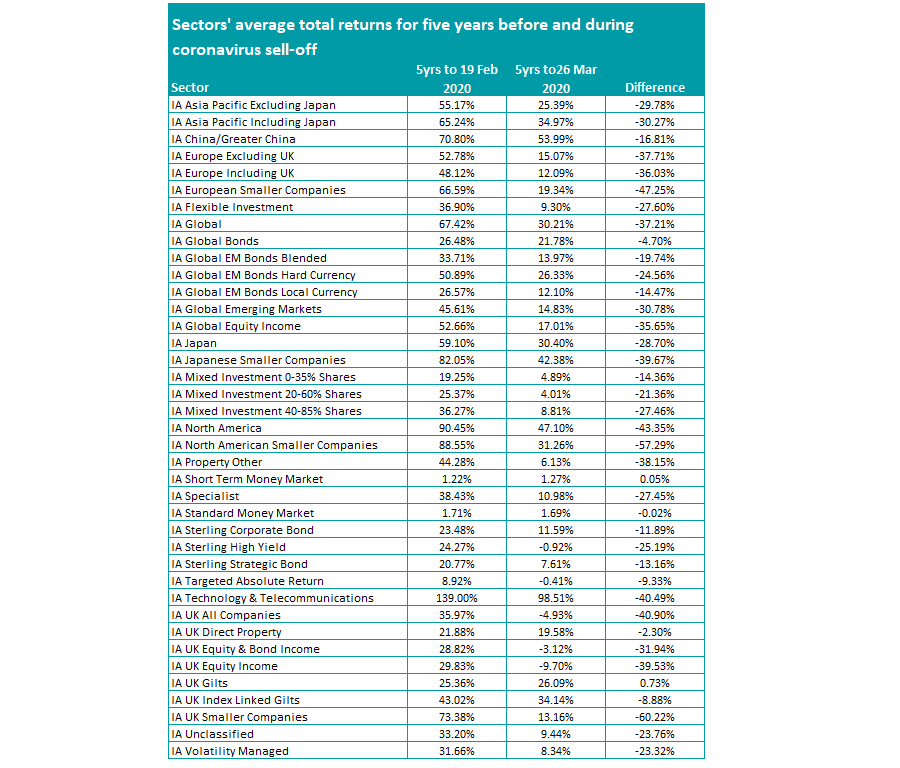
20200330_top_to_bottom_coronavirus_2Download

This may be of interest to readers! (Source: Trustnet)
Filed Under: Education, Markets, Portfolios

Monday Mashup – ps

6th April 2020 by Mark Potter Leave a Comment

One of NotHarry’s readers responded to my comments this morning by asking how one might actually get some objective data on the progress of the fight back against Covid-19. Flippantly, I replied Dr Google.

Googling something like “Coronavirus treatment research” and skipping any advert style listing and the quack medicine entries (so getting to the second or third screen usually) really does work. I can see articles for The Lancet, New York Times, CNN and various science publications even on the first page. Clearly at this time, the most recent articles will likely be the most useful.

Varying the search term to read “scientific articles etc” will get a better list but you won’t be able to read more than a summary or abstract from some of the professional publisher sites.

NotHarry is a true bookworm, both traditional and electronic…

Another useful way to see what is happing is to look at graphics that show the pace of virus spread. I like the tool offered at this web address (URL) https://aatishb.com/covidtrends/. You can easily edit the list of countries whose data is shown. If you did that today and included Austria, you would immediately see why they are able to slightly relax their lockdown. You will also see why there is a lot of pain still to come, if you add the lines for the US and the UK.

Markets today have jumped at the news from Austria and less dramatic improvements in Spain and Italy, but that may be premature, in my judgement.

If you think I am too pessimistic (and I may be, of course), I suggest you might be prudent to make some modest phased allocations of cash to the markets most sold off and those best insulated from the damage already done. To me that suggests a look at the technology and innovations funds and funds investing away from the mega caps (like the FTSE 100). A passive index tracking fund with low costs might well be a simple way to dip your toe back in the water!

Filed Under: Markets, Trading

Monday mashup – what next?

6th April 2020 by Mark Potter 2 Comments

Having published a pretty gloomy synopsis at the start of the month, but also pointed out that the world is changing very fast at the moment, I think I ought to offer some pointers to prepare readers for actions when they feel the opportunity to buy back into global stock markets has arrived.

Do bear in mind that there will not be a single point in time that is the right time to buy – there will be a change in the general trajectory of the valuation graph but it will still be bumpy. Even when there is a so called ‘v’ shaped recovery, the point at the bottom of the ‘v’ may not be that sharp when looked at microscopically.

It is already clear that we are not going to get a ‘v’ shaped recovery this time. If we are lucky enough to get a ‘u’ shaped graph to look back on later, then at the moment we are travelling along the rough bottom of the ‘u’. I am inclined to think we will more likely get a ‘w’ – in other words there is another down leg to come before there can be confidence enough for a permanent climb in valuations.

What will be the advance signs – so called leading indicators – of a recovery?

Bring me sunshine?

In the short term they will all be medical: news of a reliable vaccination; treatment methods (more significant in my opinion); a change in the rate of infection in Europe, the UK and the US; relaxing of lock down measures and so on.

For there to be a quality recovery, rather than just a ‘bear market rally’ the economic prognostications must switch from the absolutely dire (as now) to the ‘not so bad as we feared’.

In the short term, news of major bankruptcies, dividend cuts or even cessation, nationalisations and so on look pretty likely to me. But that may not immediately result in a sharp sell off, more likely a more gradual decline into depression.

As the market is continuing to be to some extent in denial, I suspect that we have some time to go until we reach the final ‘capitulation’ phase. But in this case, the economic news (or at least projections) will I suspect get better after the medical news gets better and markets are well known to be anticipatory.

So I recommend reading all you can manage about progress with the research and science. Understanding when that is about to yield useful results will give you your ‘leading indicator’

Filed Under: Markets, Portfolios, Trading, Uncategorised

Monday mashup – brave new world?

23rd March 2020 by Mark Potter Leave a Comment

As I have been posting much more frequently recently to offer readers some insights during difficult times, this week’s meandering heads off into the future and attempts, Beethoven like, to find leisurely pastoral scenes after a frightening storm. But only finds something less attractive.

So this is an opinion piece and you can stop reading now if you were only expecting market commentary.

A potted history

I have read some serious commentators (Andrew Rawnsley in The Observer, for example) pointing out that the reaction of the UK government to the coronavirus threat effectively makes a bonfire of everything Conservatives in the UK claimed they believed in. For very good reasons, the UK will have a public spending budget not seen since WW2, life dictated at a microscopic level by the state (not nanny state, more like Big Brother), nationalised railways (just to start, wait for more), enhanced State benefits and so on.

My thinking has for a few weeks been that whatever the economic consequences of the virus, there will in time be a seismic change in the relationships and rewards in the capitalist system.

The world will be different for investors from now on, I think

When I was training to be a Chartered Secretary, just pre-Thatcher in the 1980’s, we were taught that big companies were ideally governed in the interest of stakeholders, not just shareholders. Other interests might include employees, pensioners of the business, consumers, the environment and even the public purse. In those times there was much talk of putting representatives of these other interest groups, especially employees, on company boards.

That seemed civilised to me. The large corporates have been identified as self perpetuating entities that in some cases are larger and more powerful than governments right back to the days of the Dutch East India Company, who had the largest military in the world. We have had the American ‘corporate robber barons’ like Carnegie, Rockefeller, van der Bilt and maybe now Zuckerberg and Bezos effectively controlling important parts of the largest global economies.

The US writer Thomas Pynchon suggests that the already completed phase of evolution after humanity is the American Corporation. Y N Harari in his best selling book ‘Sapiens’ explores at some length the management of human interests by corporations and collective systems, with the obvious diametric opposite to the corporation being the truly Communist state, like North Korea.

In response to the outrageous use of power by the owners of corporations, the USA developed anti-trust legislation and anti-monopoly law was a big discussion topic when I was studying economics. In those days everyone feared IBM! As a student I felt that checks and balances were at least an objective of the elected representatives in a democracy.

Come the mid 1980s and Reagan and Thatcher and the world changed totally, switching hugely in favour of capitalists (in the economic not political sense) and even more in favour of the managers (directors) of companies. As time went by, even the interest of shareholders seemed to be demoted behind the managers’ remuneration packages and the earnings of corporate lawyers, bankers and anyone powerful enough to get their nose in the trough.

Some global governments held back this rapid rebalancing of economic interests but in general the economies of those countries (say France, for example) did less well. The use and abuse of the unfettered financial system, especially in the selling of vast amounts of debt, boosted the economies of the marauding members of the even freer free market.

Problem with juggling too many balls is that if you drop one, you will usually drop the lot

The financial crisis brought that to an abrupt halt but the sinners were not just forgiven but bailed out with public money and made ready to rush off again in pursuit of directors’ remuneration and spending profit or even borrowing to buy back shares (which makes the business more of a stand alone entity, not answerable to anyone).

Of course, to keep governments sweet, it was necessary for the very biggest and often shadowy beneficiaries to spend their small change on lobbying, funding election campaigns and buying up the mass media to keep the message right. At least that has been true in the USA, the stock market capitalisation of whose businesses is more than all the rest put together (never mind the wealth not in listed shares).

A body blow, from an unexpected quarter

That potted history brings us to Covid-19. Now – The ” ” Strikes Back. Fill in the space according to your personal view of the world.

It is well known that modern capitalism only works because of insatiable consumption. Insatiable consumption will destroy the environment without major changes to the mix of goods and services consumed. If I was ‘the environment’, I would work out that my best defence strategy would be to attack the consumers and directly reduce consumption. It works really fast!

I like to look at history for lessons about cyclical changes – things like changes in world domination, plagues, technological step changes, societal evolution. Nothing is new under the sun, a wise man once wrote.

Now I am not a sci-fi writer even if my readers think I am prone to flights of fancy, and I have developed a sceptical opinion of both religion and philosophy (I am too prosaic), so will stick to observing what is happening and what might follow.

  • What is happening right now is that all over the world nation states are dictating what people and businesses do. Like they usually do in China.
  • Everyone in the UK who wanted to privatise the NHS now loves it to bits, especially those with a fever and a cough (they say there are no atheists on a sinking ship).
  • Decent business owners are directing their facilities to help out and the way companies react now will have long term impacts on their future prospects with consumers.
  • Politicians who pursued austerity to the point of (probably) killing citizens are now endorsing huge amounts of government spending and libertarians who usually want to inhibit the government’s ability to keep an eye on what we all do are not batting an eyelid at the passing of unreviewed legislation to grant powers even Mr Putin would be happy with!
  • ‘Safe’ investments in high quality bonds or fixed interested securities and even gold are being sold in huge amounts, with the only asset in demand being hard currency (probably US dollars). Portfolios whose diversity depended on the classic equity/bond mix are losing less money than the equity markets, but still losing money rapidly. Cash is king.

Unprecedented is an over-used word, but in this case it is the right one. The financial aspects are not a surprise but the political and social aspects are new to everyone who has not lived through a war.

What will that mean for the future?

History does not repeat itself, but it often rhymes, attributed to Mark Twain but probably a contraction of a more complicated analysis he made. It’s a good point nonetheless.

Of course until we see a slowdown in the rate of infections, we can’t realistically assess the future, because we have no sensible timescale nor can we measure the damage.

But we can expect the relative status of the state to move back towards the level we saw after the second world war.

Well governed businesses will more likely survive than the ‘share buyback/fat directors’ bonuses’ businesses that may have been stock market darlings until now. So the mix of interests and actors in the financial world will be different, just as it was after the 2008 crisis.

That means we as investors need to think very carefully not just about the countries and sectors we invest in (at decent prices), but to focus on the sort of companies, especially in terms of sustainability and governance. And I would add another letter to the ESG acronym – T – ESGT, for environment, sustainability, governance and tax paying.

All the borrowing we are now seeing will potentially go into asset prices if governments don’t change their tactics on taxation. I think this time they they will expect a payback from business for preserving the daily heroin fix of consumption. And they may even be supplying the ‘methadone’ of public spending as a substitute.

It probably goes too far to say that capitalism is going into rehab but it will need to moderate its habits.

Filed Under: Economics, Markets, Politics, Portfolios, Rants

Clues? (m)

21st March 2020 by Mark Potter Leave a Comment

You need to be logged in to view this content. Please Log In. Not a Member? Join Us

Filed Under: Asset Allocation, Education, Markets, Portfolios

When will markets hit the bottom? (m)

19th March 2020 by Mark Potter Leave a Comment

The facile answer to that is that we will only know after the event!

The message I want to convey today is that stock market values fall most dramatically when the cycle that precedes the fall was longest and had extended into ‘over valuation’. But that is not just because confidence is eroded and people start to think about investing on a valuation rather than a momentum basis.

You need to be logged in to view the rest of the content. Please Log In. Not a Member? Join Us

Filed Under: Markets, Members Only

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 24
  • Page 25
  • Page 26
  • Page 27
  • Page 28
  • Interim pages omitted …
  • Page 37
  • Go to Next Page »

Primary Sidebar

Recent Posts

  • Deep Dive – November 2026 (Part 2)
  • Deep Dive – November 2026 (Part 1)
  • A little foresight?
  • Mid-Month Musings – Snippets
  • Deep Dive – October 2026

Archives

Categories

  • Academic theory
  • Announcements
  • Asset Allocation
  • Basics
  • Cost of investing
  • Economics
  • Education
  • Funds
  • House rules
  • Humour
  • Innovation
  • Markets
  • Members Only
  • Monthly commentary
  • News
  • Opinion
  • Passives and Trackers
  • Politics
  • Portfolios
  • Rants
  • Research tools
  • Site Content
  • Sustainability/ESG
  • Trading
  • Uncategorised