Pottering About
Last month’s article taken together with my weekly blogs since have exhausted my capacity for pontification on the direction of markets. I will not write anything new on that subject here, but for ease of reference, I reproduce below the conclusion of my January briefing.
- Fixed income assets with higher duration look much more attractive although buying now would be for early adopters who may see some losses before they get rewarded. Personally, I often both buy and sell an asset class a little early.
- Quality global growth companies are oversold due to the over discounting of future growth for higher interest rates that won’t last that long. Businesses with strong market share, pricing power and large customer bases buying products that don’t need re-inventing are currently at very fair prices, maybe below half price on what they were 18 months ago.
- If recessions are not long and deep, smaller company funds are well paced to bounce back faster than funds that are mostly mega cap and into energy stocks.
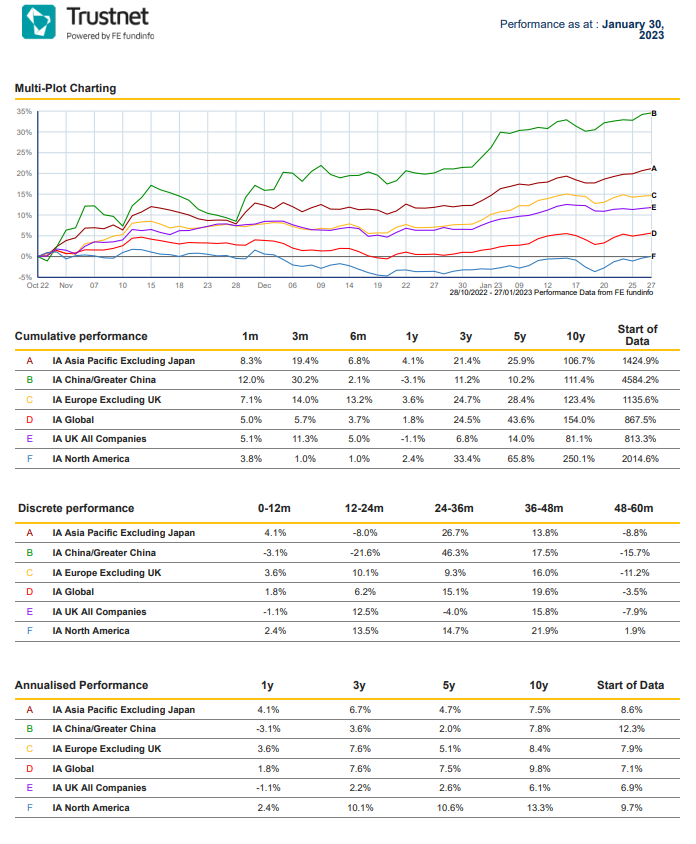
- Geographically, the North American market looks to me to be the least risky, Europe is probably priced for more risk than is realistic and UK businesses can (surely?) only have better times ahead after the almost eternal blundering of the political classes for many years. In the Asia Pacific region, Japan may for once be a profitable call as the Yen has potential to strengthen (Japan is the only place where they probably welcome inflation!) and China looks to me to be a market still with potential but undermined by politics. Other emerging markets may well benefit from China’s less friendly positioning to the USA and Europe.